5 minEconomy
Bank of Japan Raises Interest Rates to 31-Year High
The Bank of Japan lifted its benchmark interest rate to a 31-year high, citing underlying inflation that is approaching its 2 percent target. Investors weighed the move as a signal that the era of ultra-loose monetary policy is ending.
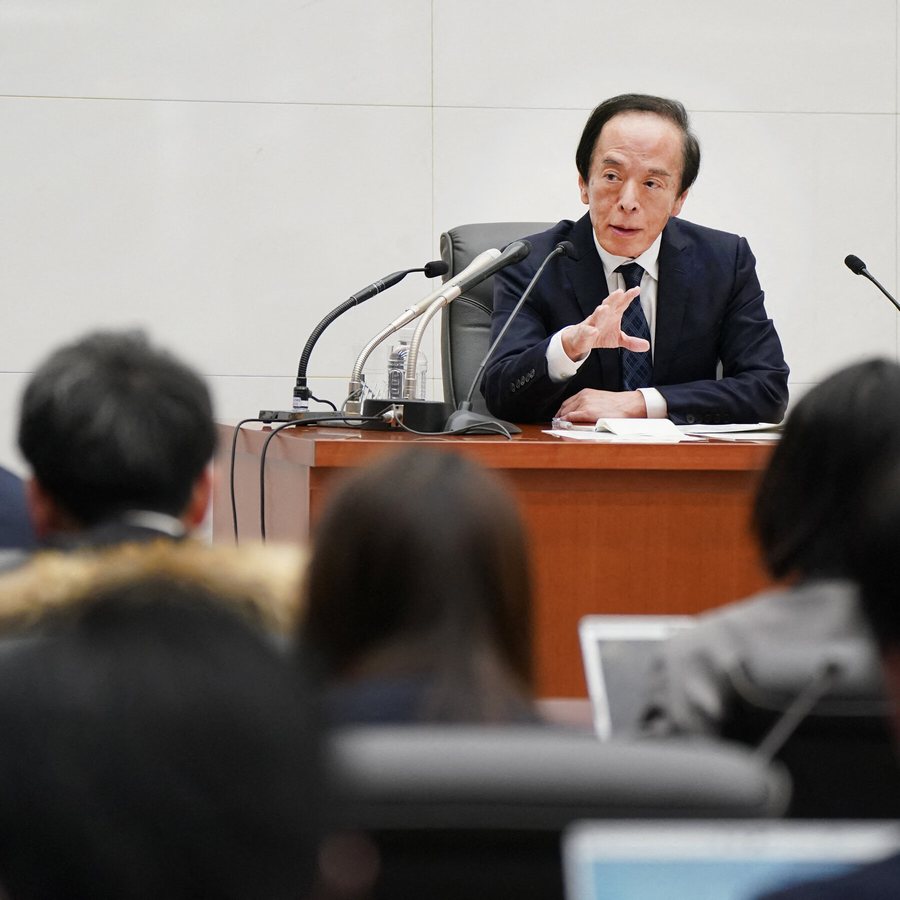
The Bank of Japan raised its benchmark interest rate to a 31-year high, a decision that marks a decisive shift away from the ultra-loose monetary policy that defined the Japanese economy for a generation. The move, announced by Governor Kazuo Ueda, reflects the central bank's growing confidence that underlying inflation is finally approaching its long-elusive 2 percent target.
Ueda indicated that price pressures have become broad enough to justify higher borrowing costs, after months of steady signals from the central bank that a policy shift was coming. The decision puts Japan's rates at their highest level since the early 1990s, a period when the country's asset bubble was collapsing and setting the stage for decades of stagnation.
Investors reacted with a mix of caution and relief. Markets had largely anticipated the move, but the pace of future increases remains uncertain. Japanese government bond yields rose, while the yen strengthened modestly against the dollar before giving back some gains. Equity markets in Tokyo were volatile, with exporters sensitive to currency swings and banks benefiting from the prospect of wider lending margins.
The rate hike carries global significance. Japan has been the world's most reliable source of cheap funding for decades, with its near-zero rates encouraging Japanese investors to pour capital into overseas assets. A sustained rise in domestic yields could pull some of that money home, tightening financial conditions in the United States, Europe, and emerging markets.
The decision also reflects a broader normalization of monetary policy after years of aggressive stimulus. The Bank of Japan was the last major central bank to hold rates near zero while the Federal Reserve and the European Central Bank raised borrowing costs to combat post-pandemic inflation. Now, with Japanese inflation running above target for an extended period, the BOJ is playing catch-up.
Ueda has emphasized that future moves will depend on data, particularly wage growth and consumer spending. The central bank wants to see a virtuous cycle in which rising wages support demand and keep inflation sustainably near 2 percent. Recent wage negotiations have delivered the strongest gains in decades, giving policymakers some reassurance.
Still, risks remain. Japan's economy is heavily indebted, and higher rates will increase the cost of servicing government debt, which is already the largest among advanced economies. Households with mortgages and businesses with variable-rate loans will feel the pinch. A sharp slowdown in consumption could derail the recovery.
The political context adds another layer. The rate hike comes amid pressure from the United States, which has long argued that Japan's weak yen and ultra-low rates give its exporters an unfair advantage. A stronger yen would help ease trade tensions, but it could also hurt Japanese manufacturers by making their goods more expensive abroad.
For global investors, the BOJ's move is a reminder that the era of free money is ending everywhere. The question now is how fast Japan will normalize and whether its economy can withstand the transition. Ueda has signaled a gradual approach, but markets will test that resolve with every new inflation reading and wage report.
The decision also has implications for currency markets. The yen has been under pressure for years, hitting multi-decade lows against the dollar. Higher Japanese rates narrow the interest rate differential that has driven the yen lower, potentially triggering a sustained reversal. That would ripple through global trade and capital flows.
Analysts will be watching the BOJ's next policy meeting for clues on the pace of further increases. Some expect another hike within months if inflation stays elevated, while others warn that the central bank may pause to assess the impact on growth. Either way, the direction is clear: Japan is no longer the anchor of ultra-cheap money.
For American readers, the shift matters because Japan is one of the largest foreign holders of U.S. Treasuries. If Japanese investors repatriate capital, it could push U.S. borrowing costs higher at a time when the federal government is already running large deficits. The ripple effects would be felt in mortgage rates, corporate bonds, and the dollar.
The Bank of Japan's move is thus more than a domestic policy adjustment. It is a signal that the global financial landscape is changing, and that the last bastion of zero interest rates has finally begun to retreat. How smoothly that retreat unfolds will shape markets for years to come.